Accounting Funds vs Restricted Funds: What Each Actually Tracks
Your treasurer says the building campaign money is restricted. Your program director wants a separate Accounting Fund for the summer mission trip. And the board wants to see both in the same report. If these concepts feel tangled, you are not alone.
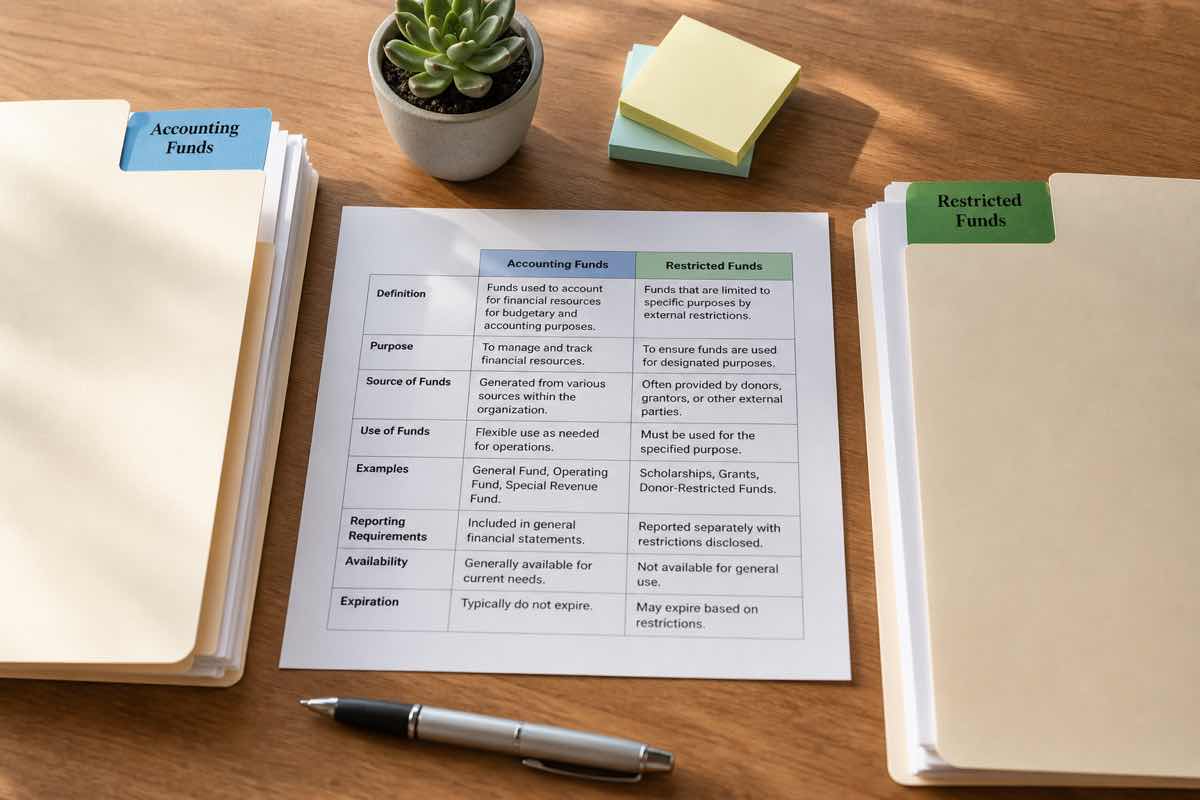
The confusion is common because Accounting Funds and restricted funds both involve separating money, but they answer different questions. One tracks where the money shows up in reports. The other tracks what the donor said you could do with it.
Quick Answer: Accounting Funds vs Restricted Funds
Accounting Funds are reporting breakdowns. They partition income and expenses so you can see activity by program, trip, or campaign without creating a separate organization.
Restricted funds track donor intent on net assets. They tell you whether money can be spent freely or is tied to a specific purpose, time period, or asset.
You need both dimensions. An Accounting Fund can hold restricted and unrestricted money at the same time. A restriction can apply across multiple Accounting Funds. They are separate layers of your financial picture, not competing categories.
For the full three-level hierarchy, see nonprofit fund hierarchy guide. For a deeper look at restriction rules and release procedures, see restricted vs. unrestricted funds.
Side-by-Side Definition Table
| Dimension | Accounting Fund | Restricted Fund |
|---|---|---|
| What it answers | Where does this activity show up in reports? | What did the donor say I could do with this money? |
| Tracks | Income and expense partitions under a fund | Net asset classification (unrestricted, temporarily restricted, permanently restricted) |
| Created by | Your internal reporting needs | Donor or grantor terms that legally bind the organization |
| Hierarchy level | Terminal partition under a parent or fund | Applies to any level: parent, fund, or Accounting Fund |
| Owns donors or giving pages | No | Restriction class is a property of the gift, not the page |
| Balance sheet | Income and expense slices for reporting | Full net asset balances by restriction class |
| Example | Honduras Trip (under Missions Fund) | A $50,000 grant restricted to youth programming |
The simplest way to remember the distinction: Accounting Funds organize your chart of accounts for reporting. Restrictions organize your net assets for compliance.
When to Use an Accounting Fund
Accounting Funds make sense when you need reporting detail inside a fund but do not need a full separate entity. Common triggers include:
-
Multiple programs under one fund. Your Youth Fund covers summer camp, after-school tutoring, and a mentorship initiative. An Accounting Fund for each lets you report revenue and expenses separately without three full funds.
-
Campaign phases. A building campaign has Phase 1 (design) and Phase 2 (construction). Accounting Funds track spending by phase while the campaign fund holds the overall balance.
-
Grant sub-projects. A federal grant funds three activities. Accounting Funds partition expenses by activity for the grant report without splitting the grant across multiple funds.
The common thread is reporting precision. You do not need Accounting Funds for every earmark or donor preference. If a donor says "I hope this supports the youth program," that is a preference, not a fund. A designated gift can stay in the Youth Fund without its own Accounting Fund unless you specifically need to report on it separately.
When Restriction Tracking Is Enough
Not every organization needs Accounting Funds. If your reporting needs are simple and your primary concern is proving that restricted dollars were spent correctly, restriction tracking alone may be sufficient.
Restriction tracking is enough when:
- You have a small number of funds and the board can see what they need from fund-level reports
- Your grants and donor restrictions are straightforward and map cleanly to existing funds
- You do not need to break down income and expenses within a fund by sub-project or sub-program
For many organizations under $500K in annual revenue, a few operational funds with proper restriction tracking on each gift is the right structure. Adding Accounting Funds too early creates reporting detail that nobody reads.
For the core mechanics of how restrictions work, see restricted funds tracking.
The Hybrid Model: Funds, Purposes, and Accounting Funds Together
Most mid-size and larger nonprofits end up with a hybrid approach. Here is a practical way to think about when each tool applies:
| Tool | Use it for | Do not use it for |
|---|---|---|
| Operational Fund | Major programs, ministries, or grant portfolios that need their own fund balance | Every donor earmark or passing campaign |
| Purpose / designation | Tracking why a gift was given (campaign, appeal, event) | Creating fund-level balances. A purpose is a tag, not a fund. |
| Accounting Fund | Reporting breakdowns when you need income and expense detail inside a fund | Replacing restriction tracking. Restrictions and Accounting Funds are separate dimensions. |
| Restriction class | Tracking donor-imposed limits on net assets (unrestricted, temporarily restricted, permanently restricted) | Organizational reporting structure. Restrictions apply to net assets, not chart-of-account segments. |
How they work together in practice
A church has a Missions Fund (operational fund). A donor gives $10,000 restricted to clean water projects (restriction class: temporarily restricted). The church creates a Clean Water Accounting Fund under the Missions Fund to track the project separately.
The restriction tracks the donor's legal intent. The Accounting Fund tracks where the spending appears in reports. When the restriction is satisfied, the net asset reclassifies from restricted to unrestricted, but the Accounting Fund keeps the reporting detail permanently.
How AlignMint Maps These Dimensions
AlignMint keeps restriction tracking and Accounting Funds as separate dimensions so they do not interfere with each other.
| Plan | Restriction tracking | Accounting Funds |
|---|---|---|
| Plus | Full restriction classes on every gift and account | Not available. Fund-level reporting covers most small-to-mid organizations. |
| Pro | Full restriction classes | Sub-Funds (Accounting Funds) available for income and expense partitions under your funds. |
| Enterprise | Full restriction classes | Sub-Funds plus multi-org management for separate legal entities. |
On Plus, you get true fund accounting with restriction tracking. That is enough for most organizations with a straightforward fund structure. Pro adds the Accounting Fund layer when your reporting needs outgrow fund-level detail.
What Pro does not yet provide is a full balance sheet at the Accounting Fund level. Accounting Funds partition income and expense activity for reporting. The full balance sheet stays at the fund and parent level.
For more on the full fund hierarchy, see nonprofit fund hierarchy guide. For board reporting workflows using nested funds, see nested funds for board reporting. For the feature page, see fund accounting.
If your current system tracks restrictions but does not let you break down reporting inside a fund, the missing piece is likely an Accounting Fund layer, not more funds or more organizations. Keep restrictions and reporting structure as independent dimensions, and your books will be cleaner for the board and the auditor.
Frequently Asked Questions
Ready to try AlignMint with your nonprofit?
Start free — set up donor tools, giving pages, and Minty. Upgrade when you need accounting.