Nested Funds for Nonprofit Board Reporting
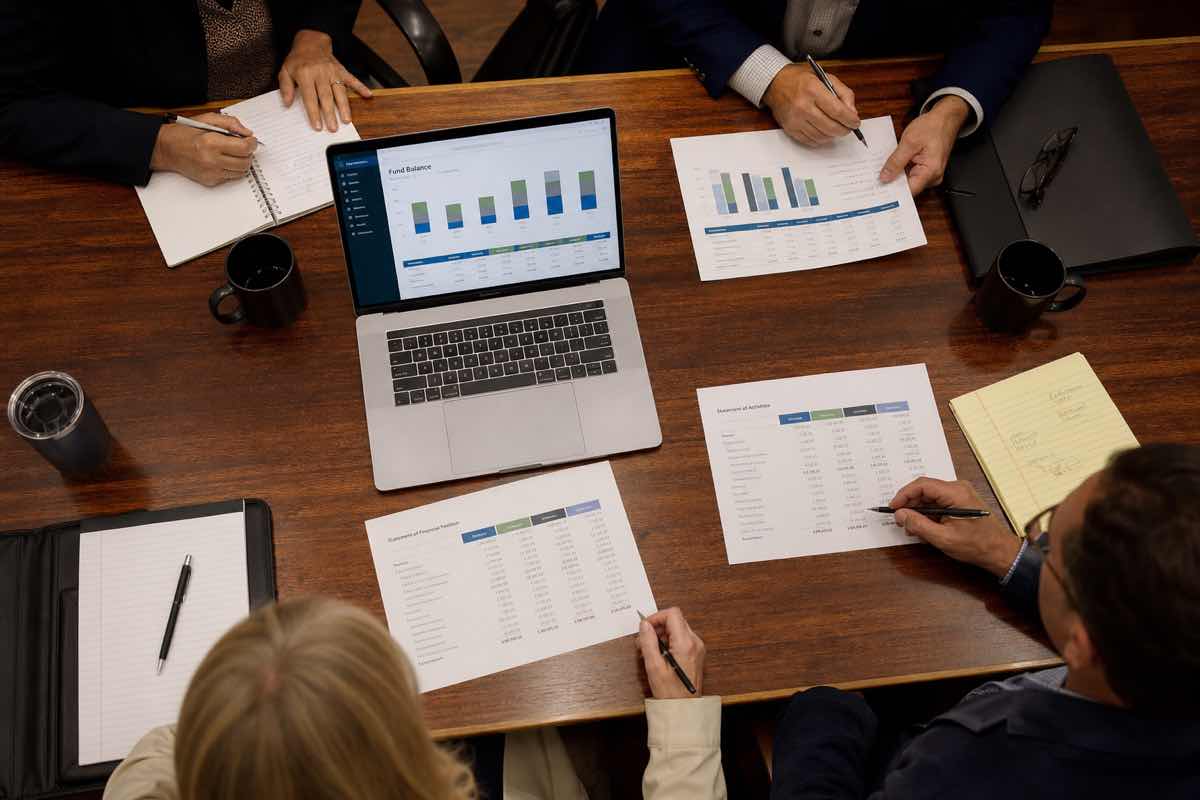
Your board meets quarterly and asks the same question every time: "How did each program do?" The treasurer opens a spreadsheet, copies numbers from the accounting system, reformats them into a table, and presents something that is technically accurate but took eight hours to build.
That workflow breaks when programs grow, grants multiply, or a new board member asks a question the spreadsheet was not designed to answer. Nested funds solve this by making fund-level reporting a filter in your accounting system rather than a reconstruction project.
Quick Answer: Nested Funds for Board Reporting
Nested funds give your board income and expense breakdowns by program, ministry, or campaign without manual spreadsheet work. Each fund carries its own activity, and Accounting Funds underneath provide finer reporting slices when needed.
The practical payoff is speed and accuracy. Instead of rebuilding a board packet from exports every month, you run the report, review it, and share it. The numbers come from the same system that recorded the transactions.
For the full three-level hierarchy, see nonprofit fund hierarchy guide. For how fund structure and restrictions work as separate dimensions, see accounting funds vs restricted funds explained.
What Boards Need to See: Org-Wide vs Fund-Level
Board members are not accountants. They need enough financial detail to govern effectively without drowning in transaction-level data. The question is always how much detail and at what level.
Org-wide view
Every board needs a consolidated picture: total revenue, total expenses, net change, and cash position. This answers "are we solvent?" and "are we on budget?" Most boards already get this.
Fund-level view
The fund-level view answers harder questions: "How did the missions program perform?" "Is the building campaign on track?" "Are restricted dollars being spent correctly?" Without fund-level reporting, these questions require the treasurer to dig through exports and rebuild the answer manually.
| Report level | What it shows | Who needs it |
|---|---|---|
| Org-wide income statement | Total revenue and expenses for the whole organization | Every board |
| Income statement by fund | Revenue and expenses for each operational fund | Boards with multiple programs or restricted grants |
| Accounting Fund detail | Income and expense partitions within a fund | Program directors, grant managers, and boards that want campaign-level visibility |
| Balance sheet | Assets, liabilities, and net assets for the organization and by fund | Finance committee, auditors, and treasurers |
Income Statement Partitions vs Full Balance Sheet by Accounting Fund
This is an important distinction that trips up a lot of organizations when evaluating software.
An income statement by fund shows revenue and expenses for each operational fund over a period. This is the core board reporting tool. Most fund accounting platforms handle this well.
Accounting Fund partitions go one level deeper. They break down income and expenses within a fund by sub-project, trip, or campaign. This is useful for grant reporting and program oversight.
A full balance sheet by Accounting Fund is a different capability. It would mean each Accounting Fund carries its own assets, liabilities, and net asset balances. Most platforms, including AlignMint's current Accounting Fund feature, do not yet support this. Accounting Funds partition income and expense activity for reporting. The full balance sheet stays at the fund and parent level.
If you need full balance sheet separation, that is usually a sign you need a separate fund or a separate organization, not a deeper Accounting Fund.
What this means for your board packet
Your board packet should include:
- Org-wide income statement (total picture)
- Income statement by fund (program-level performance)
- Fund balance summary (how much is available in each fund)
- Accounting Fund detail only where needed (grant reports, campaign phases)
That combination gives the board enough to govern without overwhelming them with detail they cannot act on.
Direct and Unassigned Activity Explained
When you use Accounting Funds, some activity will land in the fund but not be assigned to a specific Accounting Fund. This is called Direct or Unassigned activity.
It is not an error. It is a normal part of fund accounting. Shared costs like office rent, insurance, and administrative salaries often apply to the fund as a whole rather than to a specific sub-project. The same applies to general donations that support the fund's overall mission.
How to present it to the board
Show Unassigned activity as its own line in the fund report. Do not hide it or force it into an Accounting Fund where it does not belong. Board members understand that not every dollar maps to a specific sub-project.
If Unassigned activity is growing faster than attributed activity, that is a signal to review your allocation practices, not to create more Accounting Funds.
Month-End Workflow Checklist
A clean fund-level report starts with a clean month-end process. Here is a practical checklist:
- Post all income to the correct fund. Gifts, grants, and earned revenue should land in the right fund when they are recorded, not reclassified later.
- Post expenses to the correct fund and Accounting Fund (if applicable). Program expenses go to the program fund. Shared costs go to the appropriate fund or stay unassigned.
- Reconcile bank accounts. Bank reconciliation happens at the parent level because bank accounts belong to the organization, not to individual funds.
- Run the income statement by fund. Review each fund's revenue and expenses for the period. Look for miscoded transactions, unusual balances, and missing entries.
- Review Accounting Fund activity. If you use Accounting Funds, check that sub-project activity is attributed correctly and that unassigned activity makes sense.
- Check restriction status. Verify that restricted funds have not been overspent and that any releases are documented.
- Prepare the board packet. Assemble the org-wide summary, fund-level income statements, and any Accounting Fund detail the board has requested.
This process works monthly or quarterly, depending on your size and board meeting schedule. The key is consistency. A fund hierarchy that is maintained monthly produces clean reports. One that is updated only at year-end produces audit headaches.
AlignMint By-Fund Statements for Operational Funds
AlignMint's fund accounting supports nested fund reporting across its plans. On Plus, you get fund accounting with fund balance tracking and consolidated financial statements. On Pro and above, you get income statements by individual fund, Sub-Funds (Accounting Funds), and finer reporting partitions for board-ready detail.
The reporting workflow is straightforward. Select the period, select the fund (or all funds), and run the report. The numbers come from the same system that recorded the transactions, so there is no export-and-rebuild step.
For churches using this model to report by ministry, see church ministry fund hierarchy explained. For the foundational guide to fund accounting concepts, see fund accounting.
If your board is still waiting for a manually rebuilt spreadsheet every quarter, the problem is not the board's expectations. It is the reporting tool. A fund hierarchy with proper Accounting Funds turns board reporting from a project into a filter.
Frequently Asked Questions
Ready to try AlignMint with your nonprofit?
Start free — set up donor tools, giving pages, and Minty. Upgrade when you need accounting.